

Do Lab Diamonds Hold Value? A Clear UK Guide
Do lab diamonds hold value over time? Learn about resale, pricing, certification and choosing a lab-grown diamond with confidence in the UK before buying.
We Buy Gold . Top Prices Paid .
7 Day Price Promise .
30 Day Returns
Free World Wide Shipping
Life Time Warranty
We Buy Gold . Top Prices Paid .
7 Day Price Promise .
30 Day Returns
Free World Wide Shipping
Life Time Warranty
+44 203 965 6669
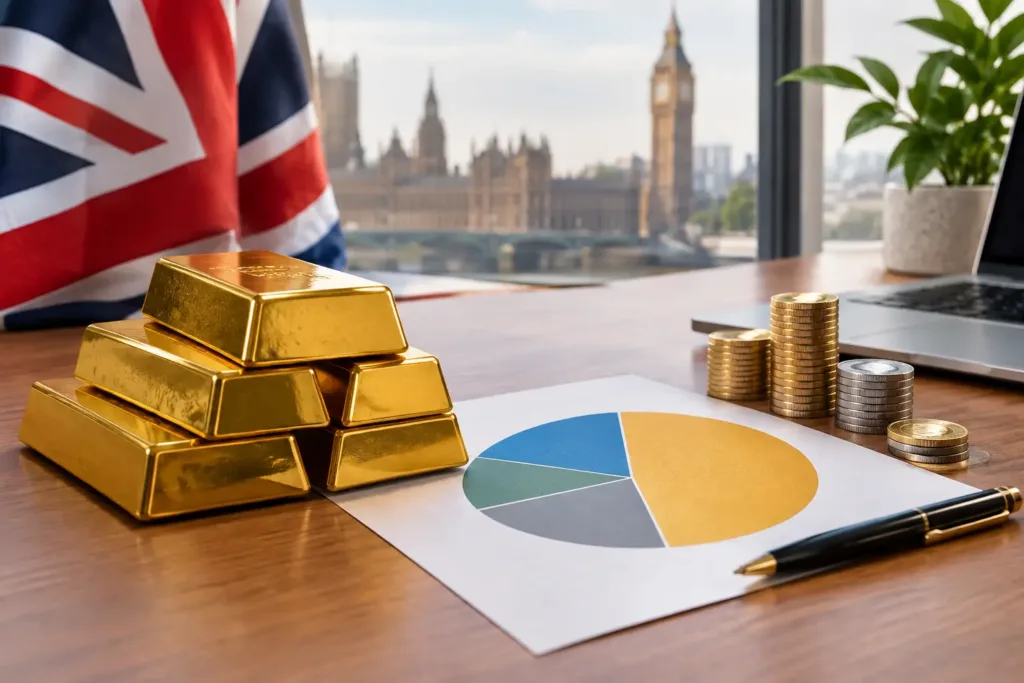
A gold holding should have a clear purpose before it has a place in your portfolio. This gold portfolio allocation example is designed for UK buyers who want the reassurance of physical 24K bullion without treating gold as a substitute for savings, income investments or a fully diversified plan.
Gold has long appealed to investors because it is a tangible asset with global recognition. It can provide diversification when confidence in currencies, equities or the wider economy weakens. However, it does not pay interest or dividends, and its price can move sharply in either direction. The right allocation is therefore personal: it depends on your financial goals, time horizon, existing assets and comfort with price movements.
Physical gold is often held as a diversifier rather than a vehicle for regular growth. Unlike a company share, a gold bar does not produce earnings. Unlike cash, it does not offer a guaranteed rate of return. Its value is tied principally to the international gold price, quoted in US dollars, alongside sterling exchange rates and the premium paid over spot when buying.
For some investors, gold is a modest long-term holding that sits quietly alongside pensions, ISAs, cash reserves and other investments. For others, it is a way to hold part of their wealth outside the banking system in a compact, internationally recognised form. Neither approach automatically makes a larger allocation suitable.
Before purchasing, keep an accessible cash reserve for emergencies and address expensive borrowing. Gold should normally be bought with capital you can leave untouched for a number of years, not money needed for a house deposit, wedding or foreseeable household expense.
There is no universal percentage that fits every investor. A practical range often considered by buyers is 5% to 15% of investable assets. The examples below show how the same asset can play very different roles depending on the size of the holding.
Imagine an investor with £100,000 of investable assets, separate from an emergency fund. A 5% allocation would mean £5,000 in investment-grade gold and £95,000 held across cash, pensions, equities, bonds or other appropriate assets.
At this level, gold is a supporting position. It may help diversify the portfolio, but a large rise or fall in the metal price is unlikely to dictate the investor’s overall result. This can suit someone who wants exposure to physical bullion while keeping the majority of their capital focused on assets intended to generate income or long-term growth.
For a purchase around this level, smaller 24K bars may offer flexibility if the investor expects to sell only part of the holding later. The trade-off is that smaller units can carry a higher premium per gramme than a larger bar.
Using the same £100,000 portfolio, a 10% allocation means £10,000 in gold. This is a more meaningful position: a significant move in the gold price will be visible in the total portfolio, but gold still does not dominate it.
This approach may appeal to an investor seeking a stronger hedge against uncertainty, sterling weakness or market stress. It can also be suitable for someone who values the certainty of owning a physical asset they can arrange to store securely.
A blended approach can be sensible. Rather than buying one very small item or a collection of tiny pieces, the investor might choose a combination of recognisable bars in sizes that balance premium efficiency with future saleability. The exact choice should reflect current pricing, preferred storage and whether partial liquidation matters.
A 15% allocation would place £15,000 of the £100,000 portfolio in gold. This may suit an experienced buyer with a strong personal view on gold’s role, substantial assets elsewhere and a realistic understanding that gold can underperform for extended periods.
The benefit is greater exposure if the gold price rises. The risk is equally clear: if the price falls, or other investments perform strongly while gold is flat, the allocation can weigh on returns. A 15% position should be a deliberate decision, not a reaction to alarming headlines or short-term price momentum.
For larger purchases, premium efficiency often becomes more relevant. Larger investment bars can have lower percentage premiums, although they are less flexible to sell in portions. Secure storage, proof of purchase and a trusted dealer’s buy-back process deserve the same attention as the initial price.
Fine gold jewellery can be timeless, meaningful and beautifully crafted, but it is not usually the most direct way to build a gold allocation. Jewellery pricing reflects craftsmanship, design, hallmarking, making charges and, where applicable, gemstones. Its resale value may not track the retail price paid.
For a portfolio allocation, investment-grade 24K gold bars are generally the clearer choice. Buyers should look for recognised, high-purity bullion with transparent weight, fineness and pricing. Eligible investment gold is generally VAT-exempt in the UK, subject to the relevant rules, which is another reason bullion and jewellery should be considered separately.
At Hispek Diamonds, customers considering physical gold can select premium 24K bullion with the confidence of clear product information and specialist support. The goal is not simply to buy gold, but to choose a format that matches the value and flexibility you need.
The spot price is only one part of the calculation. A careful buyer considers the purchase premium, delivery or storage costs, insurance and the spread between the dealer’s selling price and future buy-back price. Gold must rise enough to cover these costs before a sale produces a gain.
This is why frequent trading is rarely a natural fit for physical bullion. Gold can be more effective when viewed as a patient holding with a defined role in a wider plan. Keeping invoices, certificates and original packaging where provided can also make a later sale more straightforward.
Storage is a practical decision, not an afterthought. Home storage offers immediate access but requires appropriate security and insurance. Professional vault storage may add cost but can reduce some physical security concerns. There is no single correct answer, provided the method is proportionate to the value held and you understand who is responsible for the asset.
A smaller allocation may be more appropriate if you are still building emergency savings, have high-interest debt, expect to need your capital soon or already have substantial exposure to gold through jewellery, mining shares or funds. Owning family gold jewellery may have emotional value, but it should still be recognised when assessing overall exposure to the metal.
A larger allocation may be considered by an investor with a longer time horizon, a diversified base of other assets and a specific reason for holding more physical wealth. Even then, concentrating too heavily in one commodity can create risk. Gold’s history is long, but it does not guarantee future performance.
It is also worth separating an investment decision from a gifting decision. A 22K chain, bridal set or bespoke ring can be a lasting expression of style and sentiment. A 24K bullion bar is purchased principally for purity, value and recognisable investment credentials. Both can be premium purchases, but they belong in different parts of a financial conversation.
Ask yourself whether the proposed amount is a percentage of your investable assets rather than a figure chosen because it feels substantial. Consider how long you could hold it, where it will be stored, whether you understand the premium and how easily the chosen bar size could be sold.
You should also check the bullion’s purity, weight and recognised provenance, and deal with a retailer that provides transparent documentation and professional customer support. For significant purchases, independent financial advice can help place gold within your wider tax, pension and investment position.
Gold can bring a valuable sense of permanence to a modern portfolio, but its greatest strength is usually discipline. Choose an allocation you can explain, buy recognised bullion with care, and allow the holding to serve its intended purpose rather than chasing the next market headline.
Do lab diamonds hold value over time? Learn about resale, pricing, certification and choosing a lab-grown diamond with confidence in the UK before buying.
Learn how to choose diamond studs with confidence, comparing carat, cut, secure settings, certification and natural or lab-grown diamond options.
Find the best bridal jewellery sets for your wedding, from diamond and gold styles to practical advice on quality, comfort, value and matching beautifully.
Compare certified versus uncertified diamonds with confidence. Learn what grading reports prove, when they matter, and how to buy with clarity today.
Understand the top reasons to buy gold bullion, from portfolio diversification and VAT efficiency to ownership, liquidity and confidence for UK buyers.

Use this bullion taxation guide to understand UK VAT, Capital Gains Tax and inheritance considerations when buying, selling or gifting investment gold.