

No products in the cart.

Bullion Taxation Guide for UK Gold Investors
Use this bullion taxation guide to understand UK VAT, Capital Gains Tax and inheritance considerations when buying, selling or gifting investment gold.

We Buy Gold . Top Prices Paid .
7 Day Price Promise .
30 Day Returns
Free World Wide Shipping
Life Time Warranty
We Buy Gold . Top Prices Paid .
7 Day Price Promise .
30 Day Returns
Free World Wide Shipping
Life Time Warranty
+44 203 965 6669
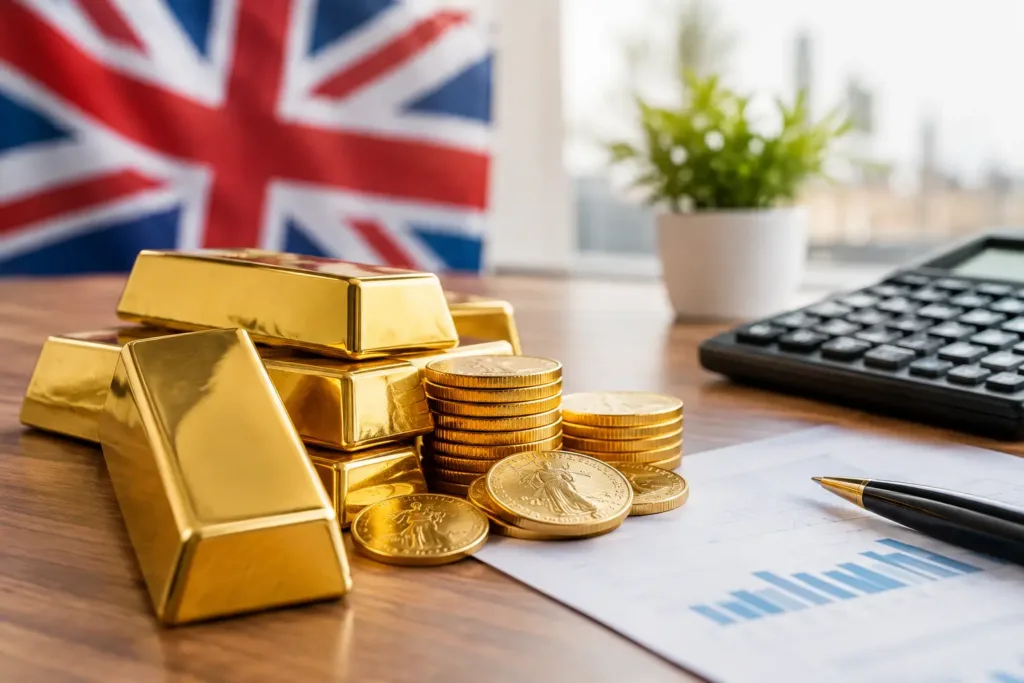
A gold bar’s price is only part of its value story. The tax treatment of what you buy, how you hold it and when you sell can materially affect your return. This bullion taxation guide explains the main UK considerations for private investors buying physical precious metals, with particular focus on investment-grade gold.
Tax rules can change and individual circumstances matter, particularly where assets are inherited, gifted, held in a business or bought overseas. Treat this as a clear starting point, then seek advice from a qualified tax professional before making a decision based on your own position.
One of the strongest practical advantages of qualifying investment gold is that it is normally exempt from VAT in the UK. This is why many investors choose 24K gold bars or eligible gold coins rather than jewellery when their primary aim is wealth preservation or portfolio diversification.
For a gold bar to qualify as investment gold, it generally needs to meet recognised purity and market standards. Bars of at least 995 fineness are usually eligible, which includes many LBMA-approved 24K investment bars. Eligible gold coins must meet specific conditions relating to purity, year of minting, legal tender status and sale price.
VAT exemption does not mean every gold item is VAT-free. Gold jewellery, even high-carat pieces, is ordinarily subject to VAT when sold by a UK retailer. Jewellery includes craftsmanship, design and wearability alongside its metal content, so it is purchased and taxed differently from bullion. Silver, platinum and palladium bullion are also generally subject to VAT, making their entry cost different from qualifying investment gold.
This distinction matters when comparing products. A 24K investment bar may be a more tax-efficient route for an investor focused on metal exposure, while a 22K chain or a diamond-set piece offers personal enjoyment, design and gifting value. They serve different purposes and should not be assessed on headline gold weight alone.
When you sell bullion for more than you paid, the gain may be subject to Capital Gains Tax, commonly shortened to CGT. For most private investors, gold bars are chargeable assets. That means you should keep clear records of each purchase, including the purchase date, price, invoice, delivery costs and any selling costs incurred later.
Your taxable gain is not simply the difference between the purchase price and the sale price. Allowable costs can usually be taken into account when calculating the gain, provided they are directly connected to acquiring, maintaining or disposing of the asset. Professional tax advice is worthwhile where a holding has been built up over many purchases or where records are incomplete.
Each individual has an annual CGT exempt amount, but this allowance has changed significantly in recent years. It should not be treated as a permanent planning tool. Above the available allowance, the CGT rate can depend on your wider taxable income and the asset involved. Gains are normally reported through Self Assessment where required, and tax is typically due by the relevant deadline following the end of the tax year.
UK legal tender gold coins can have a different CGT position. Coins such as certain Britannia and Sovereign issues are generally treated as exempt from CGT for UK-resident individuals because they are legal tender in the United Kingdom.
That does not mean every coin described as a gold coin is CGT-free. Overseas coins, collectible issues and non-qualifying products may be treated differently. Nor does it mean a legal tender coin is always the best purchase for every investor. Premiums, availability, resale demand and the amount of gold received for your budget all deserve consideration.
The distinction can be particularly useful for investors who expect to build a meaningful holding over time. A balanced approach may include VAT-exempt gold bars for efficient metal value alongside qualifying UK legal tender coins for potential CGT efficiency. The right mix depends on your budget, time horizon and preferred exit route.
It is also worth understanding the other side of the rule: if a gain on a CGT-exempt coin is not taxable, a loss on that coin is generally not available to set against taxable gains elsewhere. Tax treatment should support an investment decision, not replace one.
Physical bullion is straightforward to own, but it should be documented as carefully as any other valuable asset. Retain original invoices, certificates where supplied, photographs of serial numbers on bars and correspondence relating to sales. Store digital copies separately from the bullion itself.
When you sell, obtain a clear record of the buyer, date, quantity, product description and proceeds received. This helps you calculate any gain accurately and supports the provenance of your holding. It can also make a future sale smoother, especially for recognised bars and widely traded coins.
For investors buying regularly, a simple spreadsheet can be enough. Record the product, weight, fineness, purchase price, relevant costs and whether the item is a gold bar, a qualifying legal tender coin or another type of precious metal product. Separating these categories from the outset avoids unnecessary uncertainty years later.
Giving bullion to a spouse or civil partner is often treated differently from giving it to another family member. Transfers between spouses or civil partners who are living together are commonly made on a no-gain, no-loss basis for CGT, although specialist advice is sensible for separation, non-UK residence or complex arrangements.
A gift to an adult child, friend or trust can be treated as a disposal at market value for CGT purposes, even where no money changes hands. In practical terms, you may need to consider a taxable gain at the point of gifting. A contemporaneous valuation and a written record of the transfer are sensible safeguards.
On death, bullion forms part of an estate for inheritance tax purposes, subject to the usual allowances, reliefs and the individual’s wider circumstances. The beneficiary normally acquires the asset at its probate value for future CGT calculations. Keeping purchase documentation and a secure inventory can make administration much easier for those dealing with an estate.
The UK VAT exemption for qualifying investment gold does not remove every tax or administrative issue when bullion crosses borders. Import VAT, customs declarations, local taxes, storage arrangements and reporting obligations can all arise depending on where you buy, where the bullion is delivered and where you are tax resident.
Overseas storage can be appropriate for some investors, but it adds another layer of due diligence. Confirm ownership terms, insurance, audit arrangements, withdrawal rights and the jurisdiction governing the storage agreement. A low advertised premium is less attractive if the tax treatment, access or resale process is unclear.
Fine jewellery should be bought first for its beauty, craftsmanship and emotional significance. Hallmarking gives useful assurance about precious metal fineness, while diamond certification can provide confidence in a stone’s stated qualities. Neither changes the fact that jewellery is normally taxed and valued differently from investment bullion.
Resale values for jewellery may reflect design, condition, brand, gemstones and prevailing metal prices. For tax purposes, personal possessions have their own CGT rules and exemptions, which can be more nuanced than the treatment of a standard gold bar. If you are selling high-value jewellery, inherited pieces or a collection, take advice before assuming that no tax applies.
The most effective tax planning usually begins before purchase. Decide whether you want a liquid store of value, a potential long-term holding, a meaningful gift or a piece to wear and enjoy. Then select a product whose purity, VAT status, resale market and possible CGT treatment fit that purpose.
At Hispek Diamonds, investors can choose certified, investment-grade 24K gold with clear product information and the reassurance of a trusted precious metals retailer. Whatever you buy, keep the paperwork, understand the tax position before you sell and let your wider financial goals lead the decision.
Use this bullion taxation guide to understand UK VAT, Capital Gains Tax and inheritance considerations when buying, selling or gifting investment gold.
Explore engagement ring upgrade examples, from larger centre stones to bespoke resets, with practical advice on value, comfort and diamond certification.

Use this bullion dealer comparison to assess pricing, product authenticity, delivery, storage and buy-back support before you invest in physical gold.
To layer 22K gold chains successfully, Hispek Diamonds plans the order before putting anything on. Different lengths create separation, compatible link structures reduce friction, and…
Ethical diamonds explained: understand sourcing, traceability, certification and lab-grown choices before choosing a ring you can wear with confidence.

The security of 22K gold jewellery depends on more than the main chain, bracelet or bangle. Clasps close the piece, hinges control opening points, and…